Loan Officer in Georgetown, Texas

Home loans, made clear.

Purchase, refinance and investor financing across Texas, Florida and Tennessee. One loan officer, your numbers in writing up front, and answers when you call.

Apply now →

NMLS #1630227 FL #LO122381 Colibri Home Loans NMLS #135622

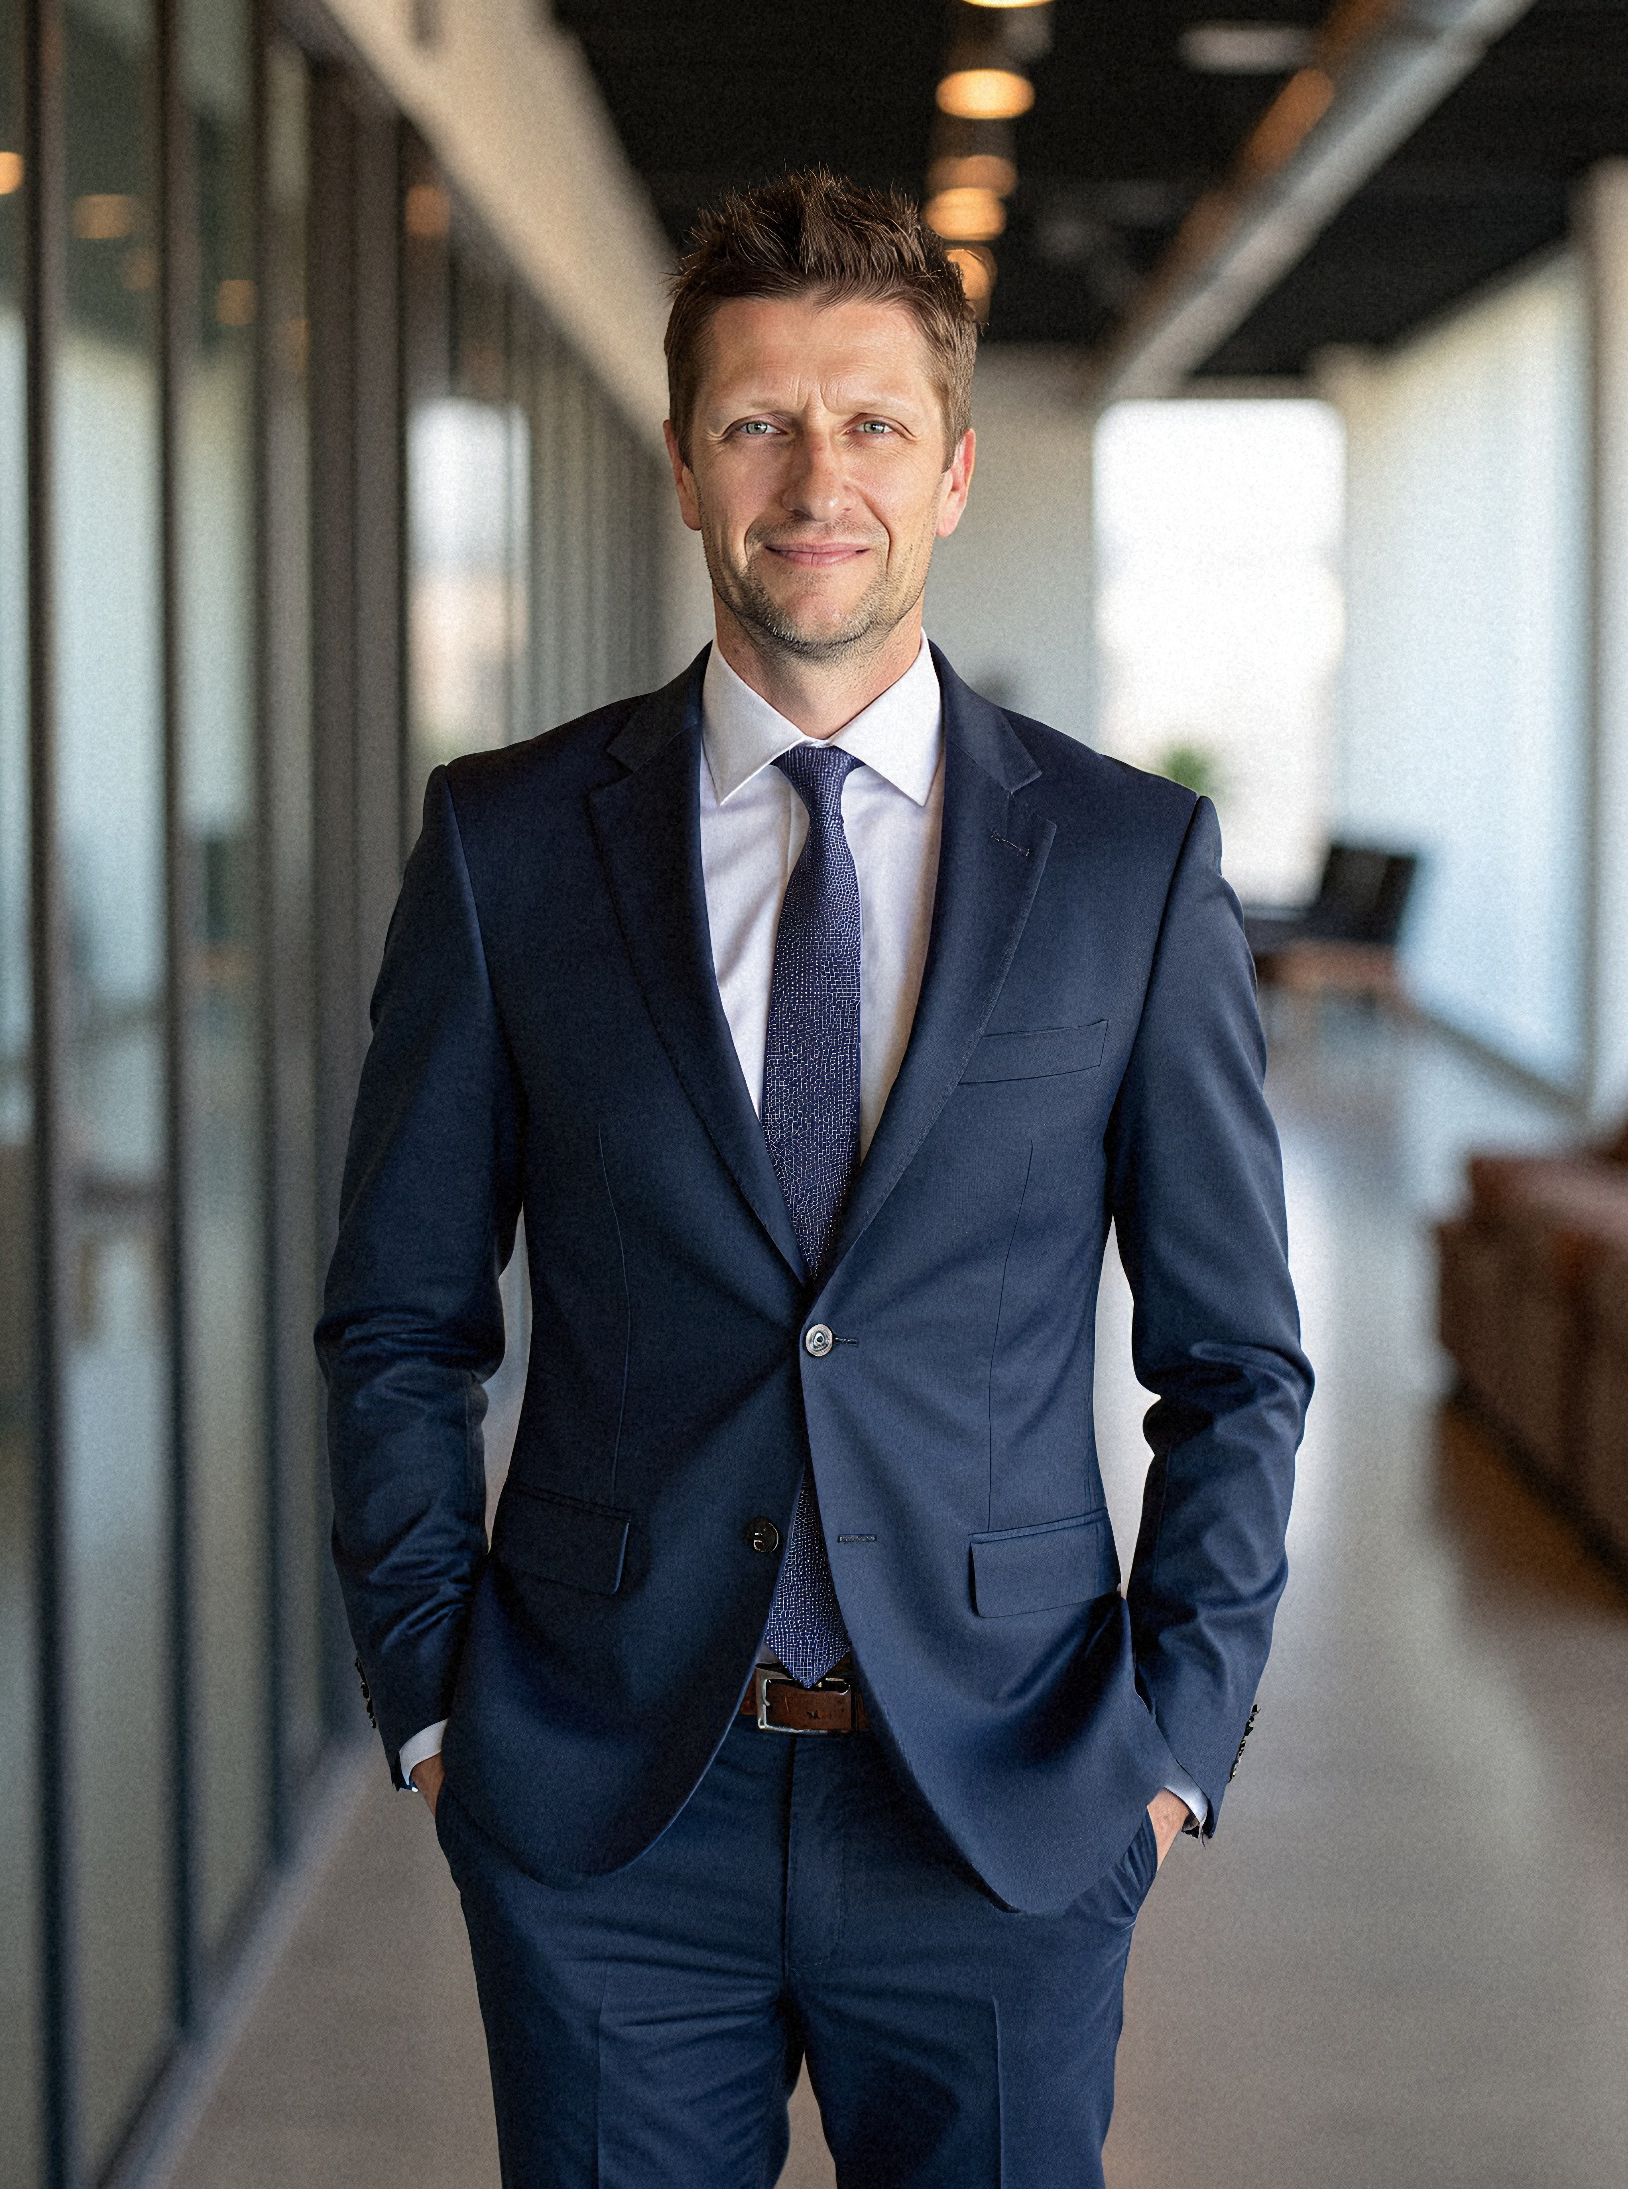
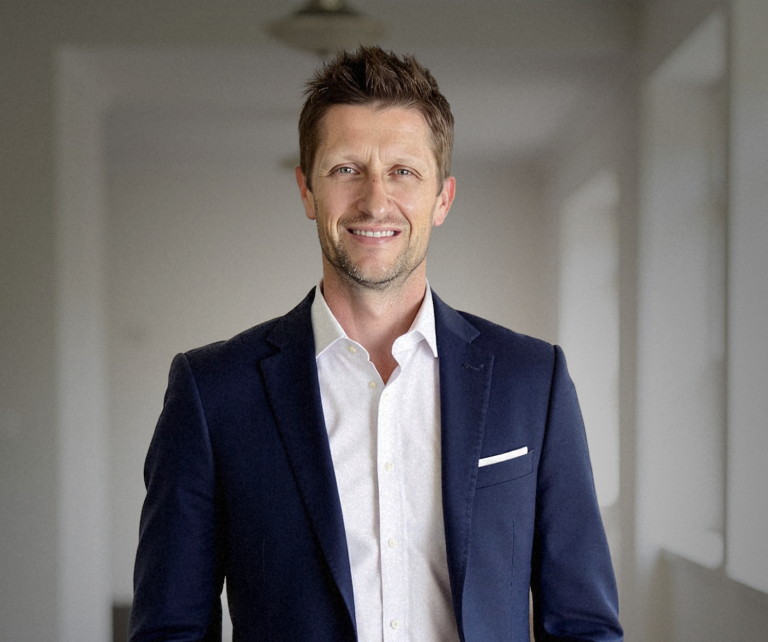
Mark Howard, Loan Officer at Colibri Home Loans
Mark HowardLoan Officer Colibri Home Loans
5.0 from 54 Google reviews Read reviews
A new homeowner holding house keys next to a model home
Serving Texas, Florida & Tennessee
Helping families since 2017 Buy, refinance, invest
  • Licensed in TX, FL & TN
  • Conventional, FHA, VA & USDA
  • Jumbo, DSCR & bank statement
  • Equal Housing Opportunity
Mark Howard, Loan Officer at Colibri Home Loans
Colibri Home Loans (512) 592-8181 mark@colibrihomeloans.com

Meet Mark

Personal guidance for a better path home.

I'm Mark Howard, a Loan Officer with Colibri Home Loans in Georgetown, Texas. Since 2017 I've had the privilege of helping individuals and families take one of life's biggest steps: buying a home.

I live in Georgetown with my wife and three boys, so I know a home is about much more than four walls. It's where families grow, investments are built and memories are made. Outside of work you'll find me with my family, at a ball game, and most importantly following Jesus Christ, whose example shapes how I serve others.

Call or text(512) 592-8181
Based inGeorgetown, TX
Licensed inTX, FL & TN
Read my story

Client reviews

Rated 5.0 out of 5 on Google.

Real reviews from Mark's Google Business Profile, updated automatically as new ones come in.

5.054 Google reviewsSee all →

How it works

Four steps, no surprises.

You always know what happens next, what it costs and who to call.

  1. 1

    Quick call

    Your goals, timeline and budget in 15 minutes. No credit pull.

  2. 2

    Plan in writing

    Programs compared side by side, with a fee worksheet before you commit.

  3. 3

    Pre-approval

    A letter your agent can attach to offers, so you shop with confidence.

  4. 4

    Close and move in

    Updates at every milestone, from appraisal to clear to close.

Loan programs

Six programs, read like a spec sheet.

General program guidelines are below. Eligibility, limits and costs depend on your situation, so treat this as a map and not a promise.

Program details summarize common guidelines and may change. Lender overlays, county loan limits and your qualifications affect what's available. Mark Howard and Colibri Home Loans are not acting as financial or tax advisors.

Mortgage calculator

See your payment, clearly.

Move any input and every figure updates. The rate shown is an example; enter the rate from your own quote.

$
$
%
%

Example rate only, not a quote or an offer. Use the rate on your Loan Estimate.

Loan term
Taxes, insurance and HOA
Estimated monthly payment
$0/mo
  • Principal and interest$0
  • Property tax$0
  • Home insurance$0
  • HOA dues$0
Loan amount$0
Total interest$0
Total of P&I payments$0
Payoff, if paid as scheduledPending
Over the life of the loan
Remaining balanceInterest paid to date
Get pre-approved with these numbers →

Estimates for illustration only. Your actual rate, payment and costs depend on credit, property, loan program and market conditions, and are confirmed in your Loan Estimate.

For real estate agents

A lender who keeps your deals moving.

Pre-approval letters your buyers can attach to offers, quick answers on evenings and weekends, and steady updates for you and your clients from contract to closing.

  • Fast, verified pre-approvals
  • Purchase, investor and self-employed programs
  • Updates at every milestone

Questions

What people ask before they apply.

Don't see yours? Mark will answer it directly, usually the same business day.

A pre-qualification is an estimate based on what you tell a lender. A pre-approval is based on documents: your credit report, income and assets are reviewed and you receive a conditional approval letter. Sellers and their agents generally give a pre-approval more weight.

It depends on the program. VA and USDA loans can allow 0% down for eligible borrowers. FHA allows 3.5% with a qualifying credit score, and some conventional programs allow as little as 3% for first-time buyers. Putting 20% down on a conventional loan avoids private mortgage insurance.

Conventional loans commonly look for 620 or higher. FHA guidelines allow 3.5% down at 580 and above. Higher scores usually mean better pricing, so it can be worth a conversation about timing before you apply.

They commonly run between 2% and 5% of the loan amount. You'll receive a Loan Estimate within three business days of applying, and a Closing Disclosure at least three business days before you sign, so you can compare the two.

Most borrowers lock once they have an accepted offer and a closing date. Lock periods come in different lengths, and longer locks can cost more. Mark will lay out the options for your timeline.

A pre-approval involves a hard credit inquiry, which can have a small, temporary effect. Credit scoring models typically treat multiple mortgage inquiries within a short shopping window as a single inquiry, so comparing lenders doesn't multiply the impact.

The principal and interest figure uses the standard amortization formula, so it's exact for the inputs you enter. Taxes, insurance and mortgage insurance vary by property and lender, which is why your Loan Estimate is the number to rely on.

Start here

Let's map out your plan and get you home.

A written fee worksheet and a pre-approval plan built around your budget. It starts with a conversation, not a credit pull.

Apply now →
Call or text Mark(512) 592-8181

Book a call

Pick a time with Mark.

Prefer to talk now? Call or text (512) 592-8181

Pre-approval

Let's build your plan.

What are you planning?

Video

Title

In production

Chapter outline